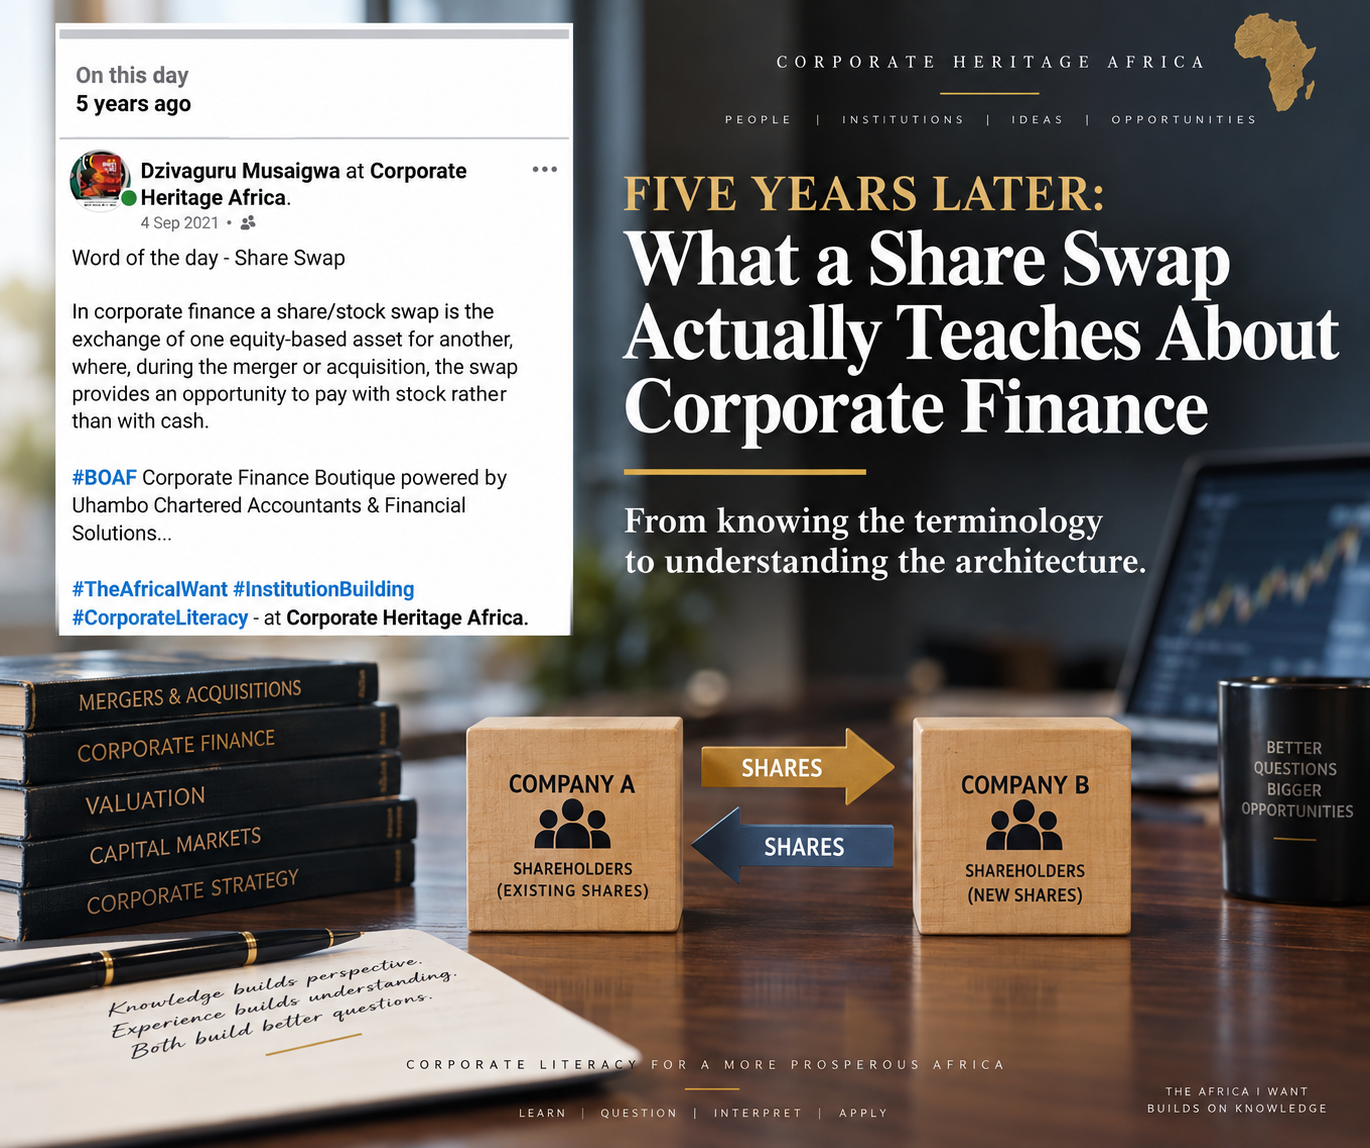
On 4 September 2021, I published a short “Word of the Day” on share swaps as part of an effort to advance corporate literacy.
Five years later, the memory interests me less for the definition I gave and more for the questions the concept now raises.
At the time, I described a share swap as the exchange of one equity-based asset for another, allowing shares to be used instead of cash in a merger or acquisition.
That captured the basic idea. But knowing the definition is only the beginning.
What is actually happening in the transaction?
Shares as Consideration
Suppose shareholders in Company A hold shares collectively valued at R100 million. Company B wants to acquire those interests but, rather than settle the transaction entirely in cash, shares in Company B form part or all of the consideration.
The transaction immediately raises a fundamental question:
How many shares in Company B should be received for each share surrendered in Company A?
That is where the exchange ratio becomes important.
Determining that ratio requires more than comparing two headline valuations. The number and classes of shares in issue, the rights attached to them, the agreed valuations of the businesses and the resulting economic interests all matter.
A valuation therefore does not remain an abstract figure in a report.
It can become part of the architecture that determines who holds what economic interest after the transaction.
When Numbers Become Rights
This is one of the aspects of corporate finance that continues to fascinate me.
Numbers can become rights.
A percentage can translate into voting power.
An exchange ratio can alter the distribution of economic interests.
A valuation assumption can materially affect the terms on which shareholders are prepared to transact.
Corporate finance is therefore not simply about calculating value. It is about structuring transactions through which economic interests are exchanged, financed and reorganised.
A transaction can involve little or no cash consideration while still transferring substantial economic value.
That distinction matters because the capacity to undertake an acquisition is not necessarily determined by the amount of cash available.
Cash Is Not the Only Form of Consideration
An acquiring company may identify an attractive transaction without possessing sufficient cash, or without considering it commercially sensible to deploy substantial liquidity, to settle the entire consideration in cash.
Equity consideration provides another possibility.
Using shares may preserve cash for operations, investment, debt obligations or other requirements. But it does not make the acquisition costless.
Issuing new shares may dilute existing shareholders. The recipients of those shares may acquire voting rights and participation in future economic benefits. Depending on the transaction, the distribution of influence may change significantly.
The more useful question in corporate finance is therefore not simply:
“Is there enough cash to do the deal?”
It is:
“How can the consideration be structured so that the transaction makes economic sense for the parties involved?”
That question opens a much wider field of possibilities.
Precision Matters
Revisiting the 2021 post also reminds me how easily convenient language can obscure corporate architecture.
It is common to hear that one company “buys another company with shares.”
That may communicate the broad commercial idea, but understanding the transaction requires looking beneath the shorthand.
Depending on the structure, shares may be issued or transferred as consideration to those surrendering their existing interests. The company, its shareholders, the shares they hold and the assets held by the company are not interchangeable concepts.
That distinction is not semantic pedantry.
It affects how acquisitions, mergers, restructurings and investment transactions are understood.
Corporate literacy begins when the language used to describe a transaction is interrogated rather than merely repeated.
From Definition to Understanding
What makes this five-year-old memory valuable to me is not whether I could define a share swap in 2021.
It is the opportunity to observe how understanding develops.
Five years ago, the principal question was:
What is a share swap?
Today, I am more interested in asking:
What assumptions produced the valuations? How was the exchange ratio determined? What rights attach to the shares? What happens to existing interests? Why was equity consideration chosen instead of cash? And, ultimately, who holds what before the transaction and who holds what afterwards?
Those questions move the conversation from terminology to transaction architecture.
Perhaps that is one of the benefits of maintaining an intellectual archive. An old post becomes more than a record of what I once wrote. It becomes a benchmark against which I can interrogate the development of my own understanding.
Five years ago, the word of the day was share swap.
Today, the lesson is broader:
Knowing the terminology allows one to enter the conversation. Understanding the architecture allows one to interrogate the transaction.