
Corporate Heritage
Knowledge Is Capital: What Ten Years Taught Me About Knowing


Published
2 months agoon

By Tinashe T. T. Mpasiri | 29 August 2026
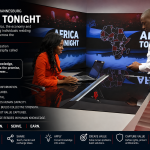
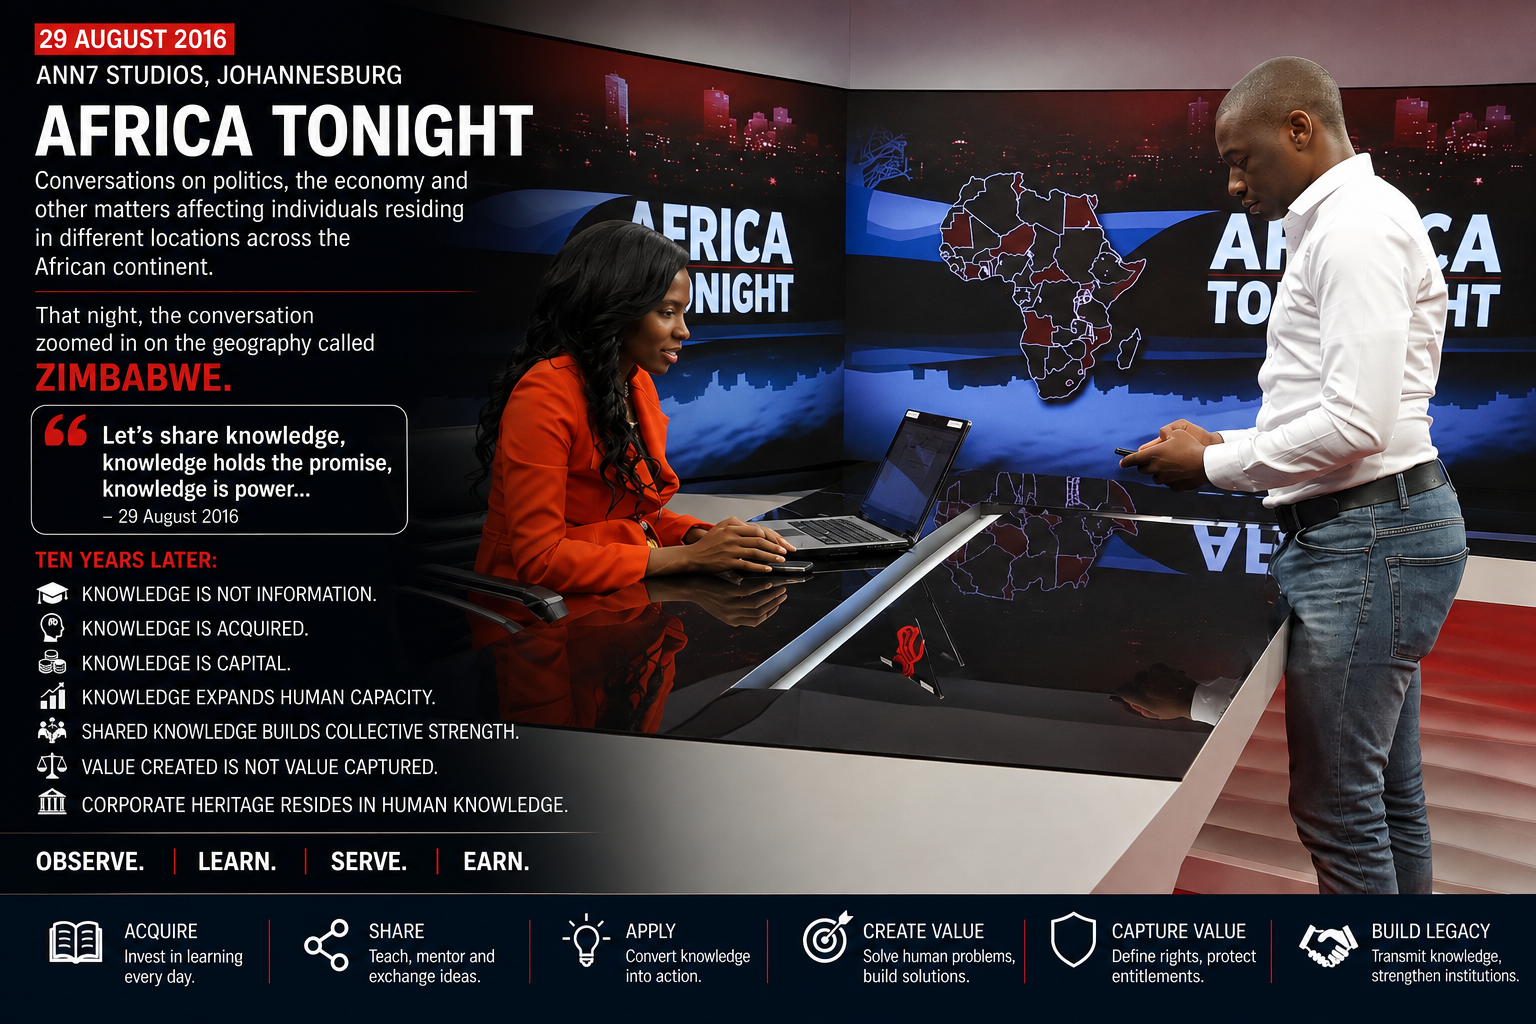
On 29 August 2016, I shared a photograph taken at the studios of ANN7 in Johannesburg, where I had participated in Africa Tonight.
The programme hosted conversations on politics, economics and other matters affecting individuals residing in different locations across the African continent. That night, the conversation zoomed in on the geography called Zimbabwe.
When I later shared the photograph, I wrote:
“Let’s share knowledge, knowledge holds the promise, knowledge is power…”
Ten years later, Facebook returned the post as a memory.
The photograph has not changed. My understanding of the proposition has.
What exactly is knowledge? What is it not? How is it acquired? And why might something that cannot be touched, stored in a warehouse or easily entered on a balance sheet constitute capital?
A man once remarked that knowledge is capital.
The proposition deserves interrogation.
Information Is Not Knowledge
Books contain information. So do contracts, financial statements, databases and the internet.
Availability does not amount to understanding.
Give the same financial statements to several people and they may see entirely different things.
One sees numbers. Another notices declining margins. Someone familiar with working-capital dynamics sees receivables stretching, inventory accumulating and cash disappearing. A corporate financier may recognise that a company reporting an accounting profit is nevertheless approaching a liquidity problem.
Nothing on the page has changed.
What differs is what each human being brings to the page.
Knowledge is therefore not merely the possession of facts. It is accumulated understanding that enables a human being to interpret information, recognise relationships, interrogate assumptions and exercise judgment.
That distinction becomes increasingly important as access to information becomes easier.
Information may be abundant. Understanding remains scarce.
How Is Knowledge Acquired?
No human being arrives knowing how to read a balance sheet, grow tomatoes commercially, interpret legislation, design a bridge or structure an acquisition.
Knowledge has an acquisition cost.
That cost may be paid through tuition, time spent reading, observation, inquiry, conversation, experimentation, apprenticeship and practice.
Sometimes the price is failure.
A transaction that collapses can expose weaknesses in assumptions, incentives and contractual arrangements. A farmer can learn from decisions made across successive seasons. A negotiator can discover that human behaviour rarely conforms perfectly to theory.
Yet experience alone does not constitute knowledge.
A person can repeat the same mistake for twenty years and describe it as twenty years of experience.
Experience becomes intellectually productive when a human being observes, interrogates, learns and adjusts.
Knowledge is therefore accumulated not simply by passing through events, but by extracting understanding from them.
Why Call Knowledge Capital?
This is where the proposition becomes interesting.
Capital is accumulated because it can contribute to future productive activity.
Machinery can increase productive capacity. Financial capital can be deployed into an enterprise. Infrastructure can reduce the cost or expand the possibilities of economic activity.
Knowledge exhibits similar characteristics.
It requires investment to acquire.
It can accumulate.
It can be deployed.
It can increase productive capacity.
It can contribute to the creation of value.
And, if neglected, it can depreciate.
Consider two human beings presented with the same problem.
One encounters it for the first time. The other has spent twenty years studying and solving variations of it.
The problem is identical.
Their capacity to respond is not.
An experienced engineer can recognise structural risks invisible to an untrained observer. A farmer may detect changes in a crop that another person walks past. A lawyer can identify consequences hidden inside apparently ordinary contractual language. A corporate financier may recognise a possible transaction where someone else sees only a distressed balance sheet.
Something economically consequential has accumulated.
That something is knowledge.
Knowledge is capital because acquiring it requires investment and possessing it can expand a human being’s capacity to produce value.
Capital That Can Compound
Knowledge also has the capacity to compound.
Understanding accounting can deepen one’s understanding of corporate finance. Corporate finance can illuminate transactions. Transaction experience can sharpen one’s appreciation of incentives and risk.
What is learned today can increase the usefulness of what was learned yesterday.
Sometimes a conversation suddenly gives meaning to something read years earlier. An experience reveals why advice once received mattered. Seemingly unrelated pieces of understanding begin to connect.
Knowledge therefore does not necessarily accumulate as isolated facts.
It develops relationships with what is already known.
Those relationships can make the whole more useful than the individual pieces from which it was assembled.
Capital That Can Depreciate
Accumulation, however, does not guarantee permanent usefulness.
Technology changes. Markets evolve. Regulations change. Scientific understanding advances. Business models disappear.
Knowledge that once created advantage can become obsolete.
A person who stops learning may believe that what they know has been preserved. In a changing environment, its productive usefulness may actually be declining.
This is why learning sometimes requires unlearning.
An assumption contradicted by evidence must be reconsidered. A method overtaken by technology must be updated. A conclusion that no longer survives scrutiny should not be defended merely because one once believed it.
Knowledge capital requires maintenance.
The Peculiar Economics of Sharing Knowledge
This brings me back to the first words of my 2016 post:
“Let’s share knowledge.”
There is something economically unusual about knowledge.
If I give another person a dollar, I surrender possession of that dollar.
If I share something I know, I do not necessarily cease knowing it.
The recipient can acquire something useful without its disappearance from the person who shared it.
A farmer can communicate lessons accumulated over thirty growing seasons. A lawyer can explain patterns recognised through hundreds of disputes. A businessperson can describe an error that consumed capital. An engineer can teach a principle learned through years of practice.
The recipient does not automatically acquire the depth of knowledge possessed by the person sharing it. Knowledge cannot simply be transferred between minds like money between bank accounts.
The listener must comprehend, interrogate, test and integrate what has been communicated.
But sharing can reduce the cost of discovery.
A lesson that took one human being ten years to acquire may take another ten minutes to hear.
The ten minutes do not reproduce the ten years of experience.
They may, however, prevent the listener from having to discover everything from zero.
Knowledge is therefore a peculiar form of capital: sharing it can expand another person’s productive capacity without necessarily diminishing one’s own.
Perhaps that is why societies, corporations and families that transmit accumulated knowledge have an advantage over those that repeatedly allow each generation to begin again.
Knowledge Is Not Action
Yet there is a danger in romanticising knowledge.
Knowing is not doing.
Knowing how a company might be financed does not finance it. Understanding agriculture does not produce a crop. Recognising an investment opportunity does not commit capital.
Knowledge expands the range of informed possibilities available to a human being.
The person must still exercise judgment, decide and act.
This is where I would revise my 2016 proposition.
I wrote:
Knowledge is power.
Today, I find that formulation incomplete.
Knowledge may increase capacity, but capacity is not an outcome.
Capital can remain idle.
So can knowledge.
Knowledge and Economic Value
Even successfully applied knowledge presents another problem.
Creating value does not automatically mean capturing it.
A person may identify an opportunity, originate a transaction, connect counterparties or solve a financing problem and still fail to participate adequately in the economic benefit produced.
The lesson is concise: valuable knowledge requires appropriate commercial architecture when it is deployed commercially.
Rights, obligations and economic entitlements matter.
That, too, is knowledge.
When the Knowledge Holder Leaves
A corporation may own factories, machinery, vehicles, intellectual property and financial assets. Then an experienced founder, executive or employee leaves.
The buildings remain. The machinery remains. The legal entity remains.
What may no longer remain accessible to those acting in the name of the corporation is the knowledge accumulated by that person: institutional memory, technical understanding, relationships, experience and judgment developed through years of decisions.
Knowledge did not walk out of the corporation.
A human being did.
The distinction is important because knowledge does not exist independently of a knower. Where knowledge has not been sufficiently documented, taught or transmitted to other human beings, the departure of the person who possesses it can reduce the productive capacity available within the corporation.
Nothing may appear under “knowledge lost” on the balance sheet. The economic consequences can nevertheless become visible in operations.
Corporate heritage therefore resides partly in the transmission of accumulated knowledge between human beings. When that transmission fails, productive capacity can be lost even though no conventional asset appears to have disappeared.
Ten Years Later
There is something fitting about encountering these questions through a photograph taken at Africa Tonight.
The programme provided a platform for conversation. That evening, Zimbabwe provided the geographical focus. Human beings supplied the experiences, arguments and ideas.
Ten years later, I return to the words accompanying the photograph:
“Let’s share knowledge.”
Those are the words I would keep.
What followed requires refinement.
Knowledge is not information merely because information is available. It is not action merely because a person understands what should be done. Nor does possessing it guarantee an outcome.
Knowledge has to be acquired. Acquisition requires investment. It can accumulate, compound, depreciate, be deployed productively and contribute to value.
And unlike many forms of capital, it can be shared without necessarily being surrendered.
That is why the proposition knowledge is capital now makes considerably more sense to me than it might have ten years ago.
The young man standing in the ANN7 studios in 2016 wrote that knowledge held promise.
I still agree with him.
But a promise is not an outcome.
Between knowledge and outcome stands a human being who must understand, judge, decide and act.
Perhaps that is the value of returning to an old Facebook memory.
A photograph reminds me where I was.
An old idea allows me to measure how far my thinking has travelled.
Observe. Learn. Serve. Earn.
#CorporateHeritage #CorporateLiteracy #TheAfricaIWant #BOAF

Over the years, I have found it challenging to define myself solely by an academic qualification, trade, or occupation. My eagerness to learn, especially about how to build and deploy capital, has allowed me to accumulate diverse experiences in a short span of time. Through this journey, I have discovered that at my core, I am a storyteller. I tell the stories of corporations, their heritage, and the individuals who act in their name. I explore the role of these institutions in fulfilling the promise of a better Africa, and, most importantly, the causal link between the rule of law and economic development. As a fellow believer in Africa’s potential, can I count on you to be a point of light in securing our continent’s future?